Calculating and reading the SYSCOHADA balance sheet
This guide shows you how to generate the SYSCOHADA balance sheet, the snapshot of your company’s net worth at a given date T, and how to read it: what the company owns (Assets), how it is financed (Liabilities) and the key ratios. SynkriaOps calculates the balance sheet automatically from your posted accounting entries: no manual input is required.
Understanding the balance sheet structure
Section titled “Understanding the balance sheet structure”Assets: what the company owns
Section titled “Assets: what the company owns”| Section | SYSCOHADA accounts | Examples |
|---|---|---|
| Fixed assets | Class 2 | Computer equipment, vehicles, land |
| Inventories | Class 3 | Merchandise, raw materials |
| Receivables | Class 4 debit balances | Customers (411xxx), Tax credits (44xxx debit) |
| Cash and equivalents | Class 5 | Bank (521xxx), petty cash (571xxx) |
Liabilities: how the company is financed
Section titled “Liabilities: how the company is financed”| Section | SYSCOHADA accounts | Examples |
|---|---|---|
| Equity | Class 1 | Share capital (101), Reserves (11xxx), Net result (12) |
| Long-term financial debt | Class 16 | Long-term bank loans |
| Short-term liabilities | Class 4 credit balances | Suppliers (401xxx), VAT payable (4431) |
| Overdrafts | Class 5 credit balances | Bank overdrafts |
Accessing the balance sheet
Section titled “Accessing the balance sheet”From the navigation bar: Accounting → Balance sheet.
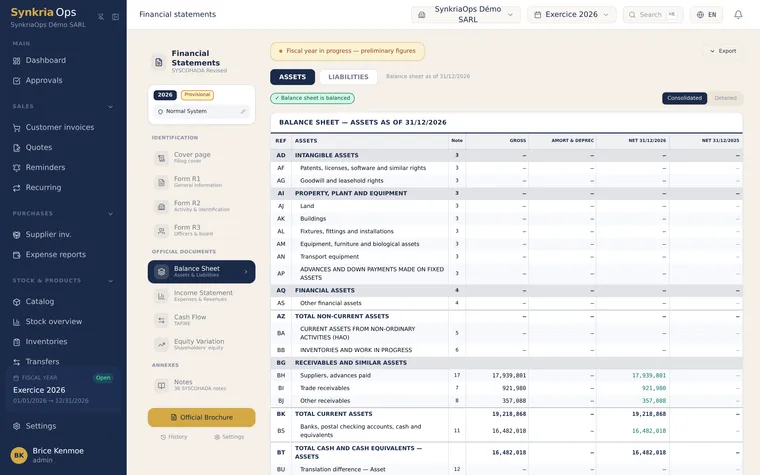
Select the fiscal year for which you wish to generate the balance sheet. SynkriaOps automatically displays columns N (selected year) and N-1 (previous year) for comparison.
Checking the prerequisites before generating
Section titled “Checking the prerequisites before generating”Before generating the balance sheet, verify the following:
-
Balanced trial balance: Open the trial balance and confirm that ΣDebit balances = ΣCredit balances.
-
All documents posted: Documents in DRAFT status are not included in the balance sheet. Post them before generating.
-
Up-to-date matching: Matched (cleared) receivables and payables do not distort outstanding balances.
-
Correct opening balances: If this is the first year after a data migration, verify that the opening balances of classes 1–5 are accurate.
-
Depreciation posted: Depreciation charges must be recorded before the balance sheet date (otherwise fixed assets will be overstated).
Reading an example balance sheet
Section titled “Reading an example balance sheet”Simplified balance sheet for a distribution SME at 31/12/2025, total balance sheet: 45,000,000 XAF.
ASSETS
Section titled “ASSETS”| Line item | N (31/12/2025) | N-1 (31/12/2024) |
|---|---|---|
| FIXED ASSETS | ||
| Equipment and tools (net) | 8,500,000 | 10,200,000 |
| Transport equipment (net) | 4,200,000 | 5,600,000 |
| Sub-total fixed assets | 12,700,000 | 15,800,000 |
| CURRENT ASSETS | ||
| Merchandise inventories | 6,800,000 | 5,100,000 |
| Trade receivables | 11,400,000 | 8,700,000 |
| VAT recoverable | 950,000 | 600,000 |
| Sub-total current assets | 19,150,000 | 14,400,000 |
| CASH | ||
| BICEC bank account (521001) | 11,200,000 | 9,500,000 |
| Petty cash (571000) | 1,950,000 | 1,200,000 |
| Sub-total cash | 13,150,000 | 10,700,000 |
| TOTAL ASSETS | 45,000,000 | 40,900,000 |
LIABILITIES
Section titled “LIABILITIES”| Line item | N (31/12/2025) | N-1 (31/12/2024) |
|---|---|---|
| EQUITY | ||
| Share capital (101000) | 10,000,000 | 10,000,000 |
| Legal reserves (1111) | 1,200,000 | 850,000 |
| Retained earnings (12x) | 2,350,000 | 1,500,000 |
| Net result for the year (12) | 7,500,000 | 5,200,000 |
| Sub-total equity | 21,050,000 | 17,550,000 |
| LONG-TERM FINANCIAL DEBT | ||
| Bank loans (162xxx) | 8,200,000 | 11,400,000 |
| SHORT-TERM LIABILITIES | ||
| Trade payables (401xxx) | 12,350,000 | 9,800,000 |
| VAT payable (4431) | 1,475,000 | 1,150,000 |
| Social security payable (422xxx) | 1,925,000 | 1,000,000 |
| Sub-total short-term liabilities | 15,750,000 | 11,950,000 |
| TOTAL LIABILITIES | 45,000,000 | 40,900,000 |
Reading the key financial ratios
Section titled “Reading the key financial ratios”Working capital (WC)
Section titled “Working capital (WC)”Working capital measures long-term financial stability:
WC = Permanent capital − Fixed assets
Permanent capital = Equity + Long-term debt = 21,050,000 + 8,200,000 = 29,250,000 XAF
WC = 29,250,000 − 12,700,000 = 16,550,000 XAF ✓ (positive = fixed assets are financed by stable resources)
Working capital requirement (WCR)
Section titled “Working capital requirement (WCR)”WCR represents the financing needs tied to operations:
WCR = Inventories + Trade receivables − Trade payables
WCR = 6,800,000 + 11,400,000 − 12,350,000 = 5,850,000 XAF
A positive WCR means operations consume cash. It must be financed (by WC or overdraft facilities).
Net cash position
Section titled “Net cash position”Net cash = Cash assets − Cash liabilities
Net cash = 13,150,000 − 0 = 13,150,000 XAF ✓
Verification: Net cash = WC − WCR = 16,550,000 − 5,850,000 = 10,700,000 XAF (slight difference due to the simplified example, in a complete balance sheet, all three ratios always reconcile).
Fixing common errors
Section titled “Fixing common errors”| Error | Likely cause | Solution |
|---|---|---|
| Total Assets ≠ Total Liabilities | Unbalanced trial balance | Correct the discrepancy in the trial balance |
| Balance sheet result ≠ income statement result | Draft document or incorrect opening balances | Post all documents, verify opening balances |
| Fixed assets overstated | Depreciation not posted | Record depreciation charges before generating the balance sheet |
| N-1 column empty | No previous fiscal year in SynkriaOps | Normal for the first year: enter opening balances via data migration |
See also
Section titled “See also”- Viewing the trial balance: An essential prerequisite before generating any balance sheet.
- Calculating the income statement: Detail of the net result that appears in account 13 of the balance sheet after year-end closing.
- Closing a fiscal year: Closing automatically calculates the result and records it in account 13.